
A fire does not only damage the house. It takes away your kitchen, your bed, your commute, and your routine, and each of those starts costing money the same night. Most policies have coverage built for exactly this, and it is one of the most underclaimed parts of a fire settlement.
It is usually called additional living expenses, and sometimes labeled loss of use on the declarations page. If you have been told nothing about it, or only that the hotel is covered for now, this is worth reading before you spend another dollar.
What Additional Living Expenses Actually Means
The coverage pays the difference between what you normally spend and what you spend because you cannot live in your home. It does not pay for everything, and it is not meant to. It pays for the increase.
Say your household normally spends $600 a month on groceries. After the fire, eating out and buying food without a kitchen runs $1,500 a month. The claim is the $900 gap, not the full $1,500. The same logic applies to housing. You keep paying your mortgage or rent as usual, and the hotel or temporary apartment is the added cost.
What Commonly Counts
Policies differ, so read yours, but these are the categories that usually qualify.
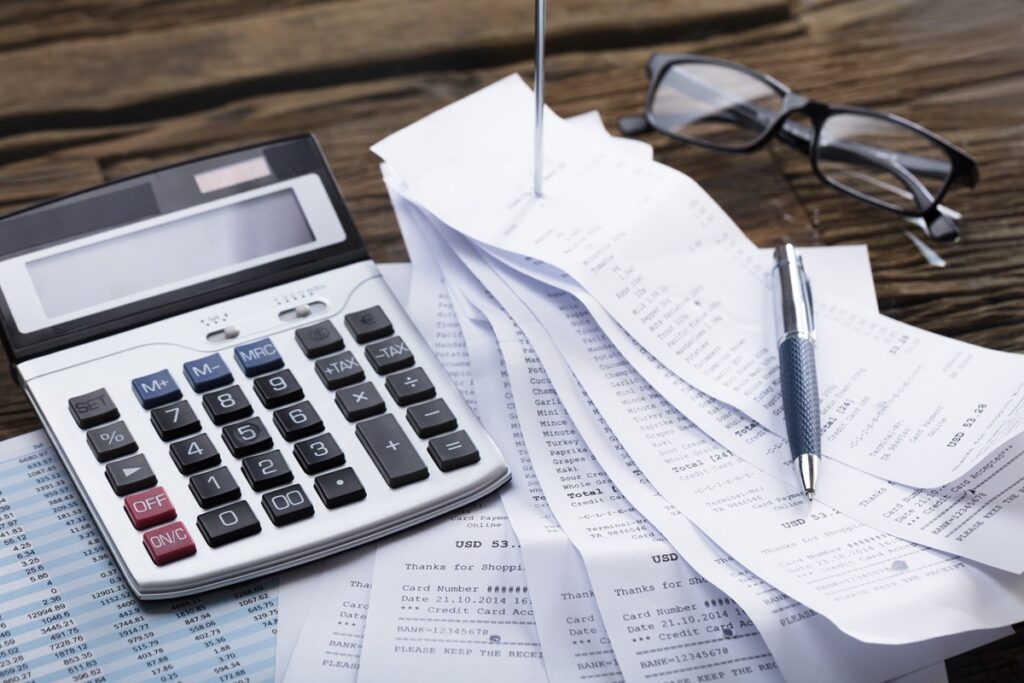
| Expense | What To Keep As Proof |
|---|---|
| Hotel, short term rental, or furnished apartment | Folios, lease, payment confirmations |
| Meals above your normal grocery spending | Receipts plus a record of your usual food costs |
| Laundry and dry cleaning | Receipts |
| Added commuting costs such as parking, tolls, transit, mileage | Receipts and a mileage log |
| Storage for belongings or rented furniture | Storage contract and invoices |
| Pet boarding | Boarding invoices |
| Moving costs and utility setup fees | Invoices and confirmation emails |
Anything that exists only because the fire displaced you is worth tracking. If you are unsure whether something counts, keep the receipt and ask. Throwing it out settles the question against you.
Whose Policy Responds
Homeowners policies typically include loss of use coverage. Renters policies and co-op and condo unit owner policies usually do too, which surprises tenants who assume renters insurance only covers belongings. Landlords generally have a separate piece, often called fair rental value or rental income, that responds when a unit cannot be rented because of a covered loss.
Find the loss of use section on your declarations page and look for two things, the dollar limit and any time limit. Some policies cap it as a percentage of the dwelling coverage, some cap it by months, and some do both.
When It Starts And When It Stops
Coverage generally applies once the home, or the part of it you need to live in, is not fit to occupy. It generally ends when repairs are finished and you can move back, or when you hit the limit, whichever comes first. A vacate order from the fire department or the city’s building authorities is strong proof that the property was uninhabitable, so get a copy.
Two fights come up here. One is the argument that part of the home is still livable and you should be staying in it. The other is the argument that repairs should have been done sooner, which shortens the period the insurer owes. In New York, permits, inspections, and contractor availability can stretch a repair timeline well past what anyone expected. Keep a record of every delay outside your control, including permit dates and emails with your contractor, so the timeline reflects what actually happened.
Comparable Housing, Not A Downgrade
The goal of the coverage is to keep your standard of living close to where it was. A family of four crowded into a studio is not comparable to a three bedroom home, and the policy does not expect you to live that way. Insurers will still push toward the cheapest option, so document why your choice is reasonable. Note the number of bedrooms you need, how close it is to work or school, whether it accepts pets, and what was actually available on short notice.
When you can, get the insurer to approve the arrangement in writing before you commit. When you cannot, because you need somewhere to sleep tonight, book it and keep the paper trail.
Mistakes That Cost People Money
Waiting for the insurer to bring it up is the first one. Many adjusters will answer questions about living expenses but will not volunteer the coverage, so ask on the first call.
Not establishing the baseline is the second. Because the claim is the difference, you need to prove what normal looked like. Pull three to six months of bank and credit card statements showing your usual groceries, commuting, and utilities.
Spending without receipts is the third. Cash purchases with no record are close to unclaimable.
Assuming that staying with family means nothing is owed is the fourth. Some policies reimburse certain costs in that situation and some do not, so ask before you decide it is a lost cause.
Signing a release before living expenses are settled is the fifth. A release can close the whole claim, including expenses that are still accruing.
Treating an advance as the final amount is the last. An early payment helps with cash flow, but it is not a ruling on what you are owed.
How To Document It
Keep every receipt, and photograph paper ones the moment you get them. Build one running spreadsheet with the date, vendor, amount, and category for each expense. Send it to the adjuster on a regular schedule, every two weeks works, rather than in one lump at the end, and send it in writing so there is a record of when it went in. Keep the hotel folios, the lease for any temporary apartment, and the storage contract. If you drive more because of the displacement, keep a mileage log.
When The Insurer Pushes Back
Slow reimbursement, denied meals, disputes over what counts as comparable housing, and arguments about when the coverage should end are all common. Ask for the policy language the insurer is relying on, in writing. If the answer is vague, or payments stall without explanation, you can file a complaint with the New York State Department of Financial Services, which regulates insurers in the state and has the authority to require a response.
Living expenses are the one part of a fire claim that grows every day while a dispute drags on, which is why leaving them unclaimed or underpaid costs more than most people realize. If your insurer is cutting off, capping, or questioning your housing costs, find out what your policy owes you for temporary housing. We work with property owners and policyholders across all five NYC boroughs and throughout New York, New Jersey, Connecticut, and Pennsylvania. No upfront cost, no fee unless we recover more than what you have already been offered.