Public Adjuster In New Jersey

Public Adjuster In New Jersey

New Jersey sits directly in Direct Public Adjusters’ backyard. Our Hackensack office put down roots here before we expanded into New York, and the relationships we’ve built with local contractors, engineers, and restoration professionals across the state show up in every claim we work. When a New Jersey property owner calls us after a loss, they’re not getting a New York company that occasionally crosses the Hudson. They’re getting adjusters who know Jersey’s housing stock, its coastal exposure, its older urban infrastructure, and the specific ways insurers operating in this market tend to minimize what they pay.

We work exclusively for New Jersey property owners and business owners. Free inspection, no upfront cost, available 24/7. If you’ve had property damage anywhere in New Jersey and the settlement number doesn’t cover what your repairs will actually cost—call us before you sign anything.

Call Us Anytime For A FREE Claim Assessment

Schedule an Appointment

Contact us for a FREE Claim Assessment

Why New Jersey Insurance Claims Require Local Knowledge

New Jersey’s geography creates insurance claim dynamics that vary dramatically from one region to the next, and understanding those regional differences is what separates a properly built claim from one that gets settled for whatever the insurer’s first offer happened to be.

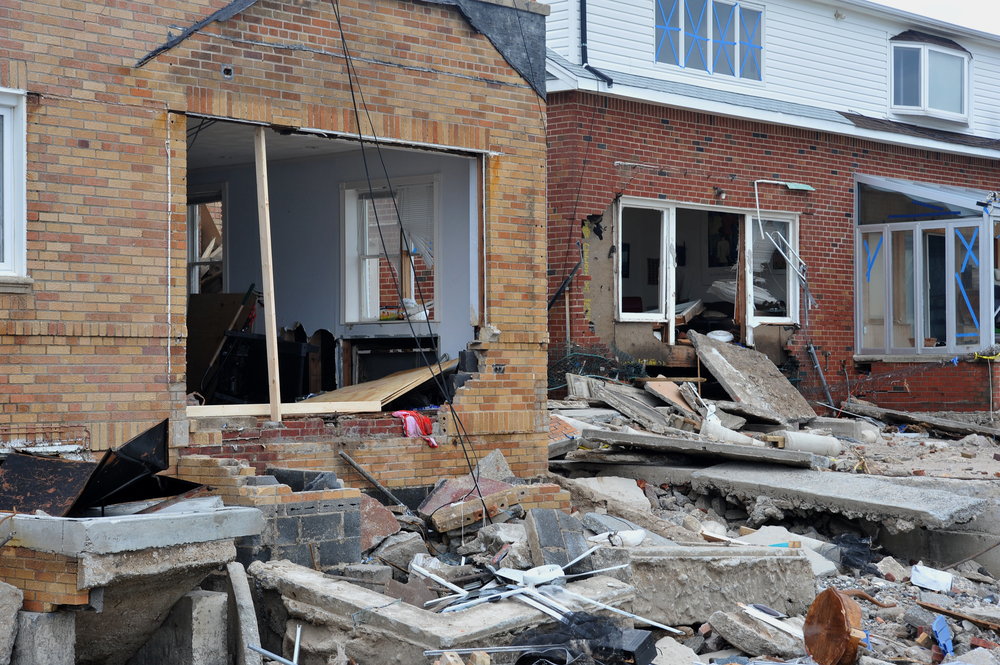
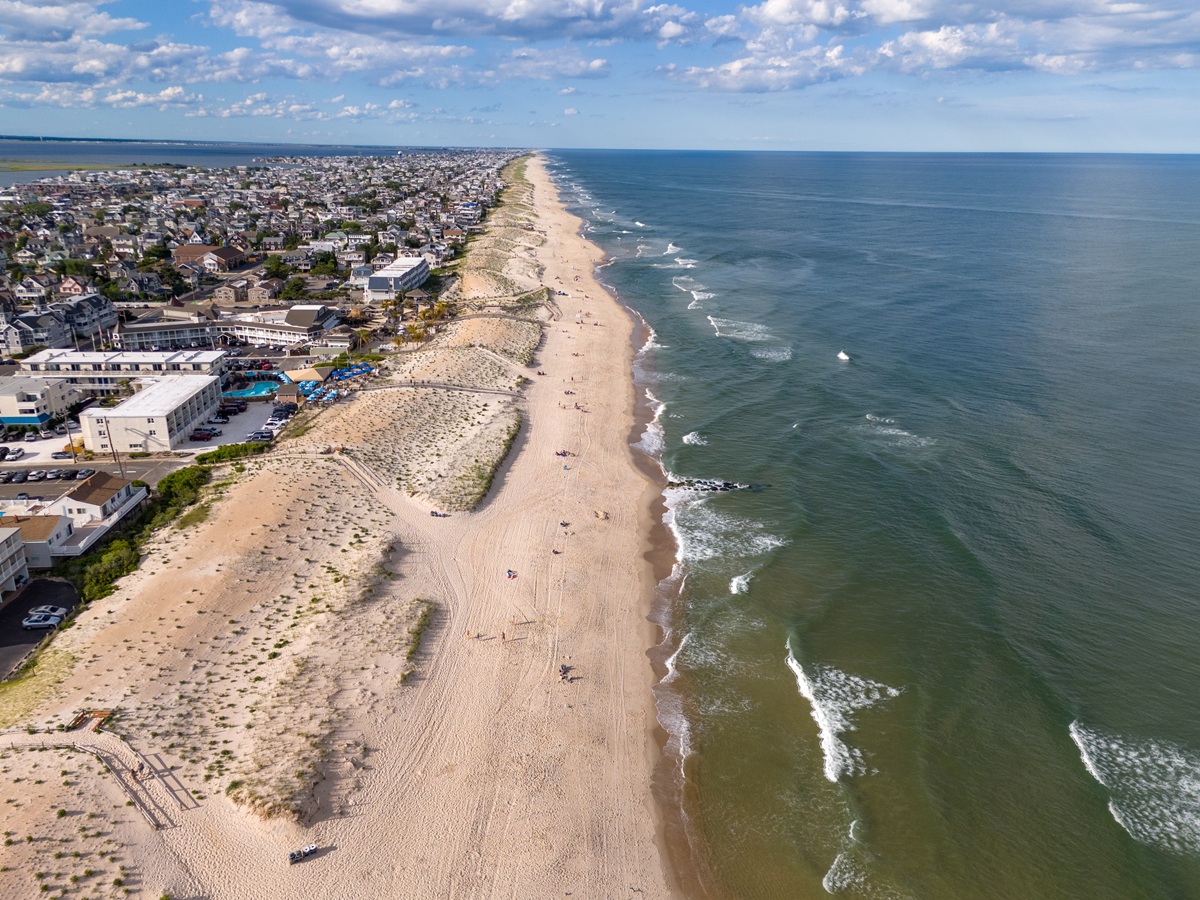
The Jersey Shore and coastal communities—from Sandy Hook down through Long Beach Island to Cape May—face storm and flood exposure that produces some of the most financially significant and most contested claims in the state. Hurricane Sandy reshaped the entire coastal claim landscape in New Jersey, and that history still matters. Properties that were damaged, claims that were settled quickly under pressure, and settlements that didn’t fully account for what was lost are still part of the landscape in coastal communities from Monmouth County through Ocean County and down to the Shore. The flood-versus-wind allocation dispute that defines coastal storm claims didn’t go away after Sandy—it shows up every time a significant storm moves up the coast, and insurers are just as motivated to push losses into the excluded flood category today as they were then.
public adjuster in new jersey

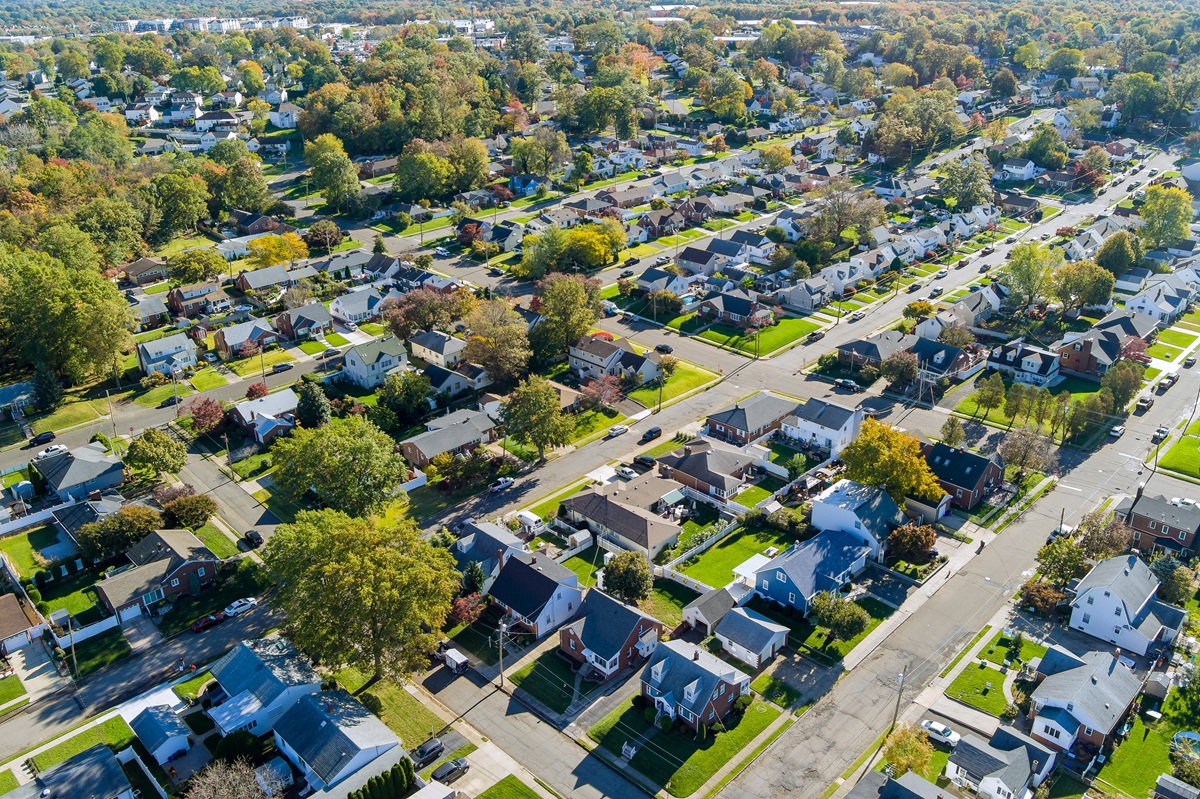
North Jersey’s urban and suburban corridor—Essex, Bergen, Hudson, Union, and Passaic counties—carries its own claim profile. Dense residential areas with older housing stock, aging multi-family buildings in cities like Newark, Jersey City, and Paterson, and a mix of residential and commercial property types that creates the same shared-system complexity we see across the Hudson in New York City. A pipe that bursts in a multi-family building in Newark travels through the same kind of shared plumbing infrastructure as one in the Bronx, and the insurer’s approach to minimizing scope is identical on both sides of the river.

Central and South Jersey presents a different picture—more suburban single-family housing, a significant commercial real estate footprint, and a large population of homeowners who’ve never filed a significant insurance claim before and don’t know what a fair settlement looks like. That demographic is exactly who insurance adjusters count on to accept whatever comes in the first envelope without pushing back.
Claims We Handle In New Jersey

Water Damage

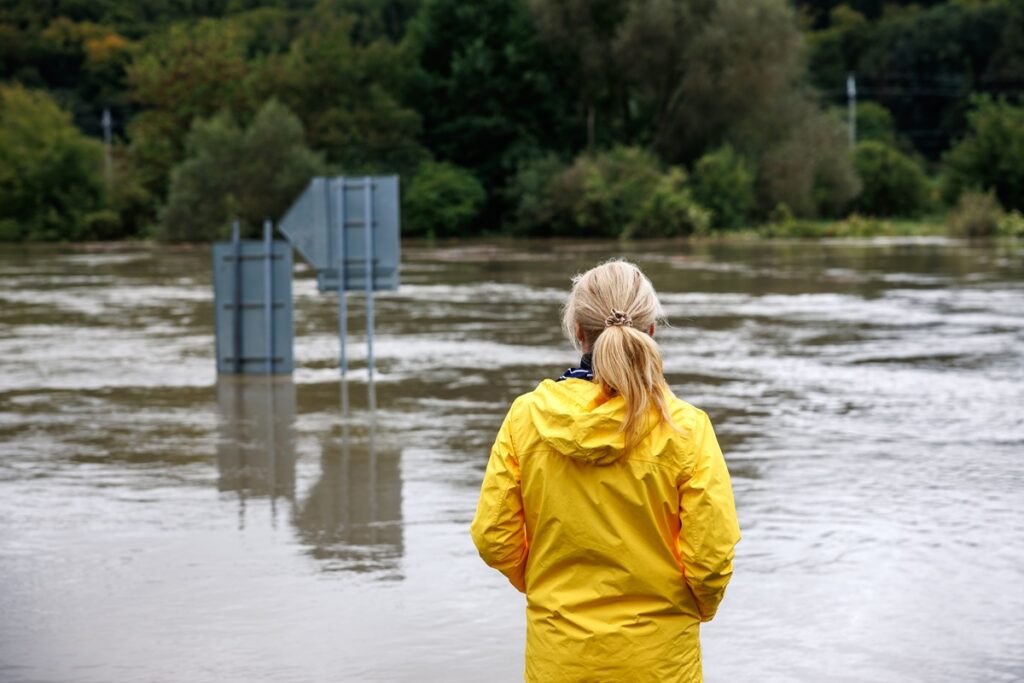
Water damage is the most common claim we handle across New Jersey. Coastal flooding, burst pipes in older residential buildings, storm-driven roof leaks, appliance failures, and in multi-unit buildings the cascading damage that happens when water finds its way through shared floors and ceilings before anyone tracks down the source. New Jersey’s winter freeze cycles hit older plumbing hard, and the wear-and-tear argument that insurers love to use on aging infrastructure is just as aggressive here as anywhere in the region. We document the full scope before cleanup starts and build the claim around what actually happened, not what an adjuster caught on a quick walkthrough.


Fire And Smoke Damage

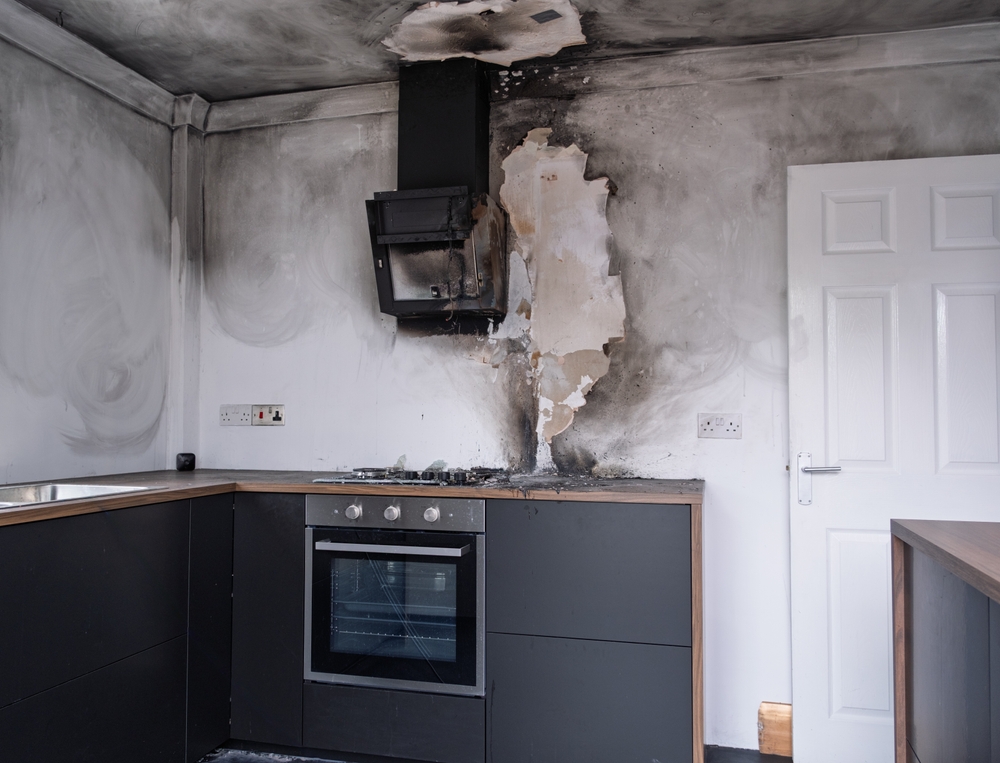
Fire and smoke damage in New Jersey’s residential neighborhoods—whether it’s a two-family in Clifton, a row house in Camden, or a converted Victorian in Montclair—spreads through shared attic space, shared walls, and shared mechanical systems in ways that insurer estimates consistently undervalue. We document the full reach of every fire and smoke claim, including the units and spaces that weren’t near the fire itself but took smoke damage through the building’s systems.


Storm And Wind Damage

Storm and wind damage in New Jersey ranges from coastal surge events that produce the most complex and most disputed claims in the state, to inland nor’easter damage that concentrates on roofing and siding across the suburban corridor, to hail events that hit the central and southern counties with regularity. The insurer’s playbook—wear and tear, gradual deterioration, flood rather than wind—gets deployed across all of these, and countering it requires weather verification data and documentation that ties the damage to the specific event.


Closed business sign representing business interruption insurance claim in Manhattan

Business Interruption

For New Jersey business owners: from the Route 1 commercial corridor to the restaurant rows of Hoboken and Montclair to the industrial parks of the Meadowlands—a covered loss that forces a closure or partial shutdown creates income losses that belong in the claim. We build business interruption claims from actual financial records, not from national averages that have nothing to do with what a specific New Jersey business generates in a specific location.

Accidental Damage

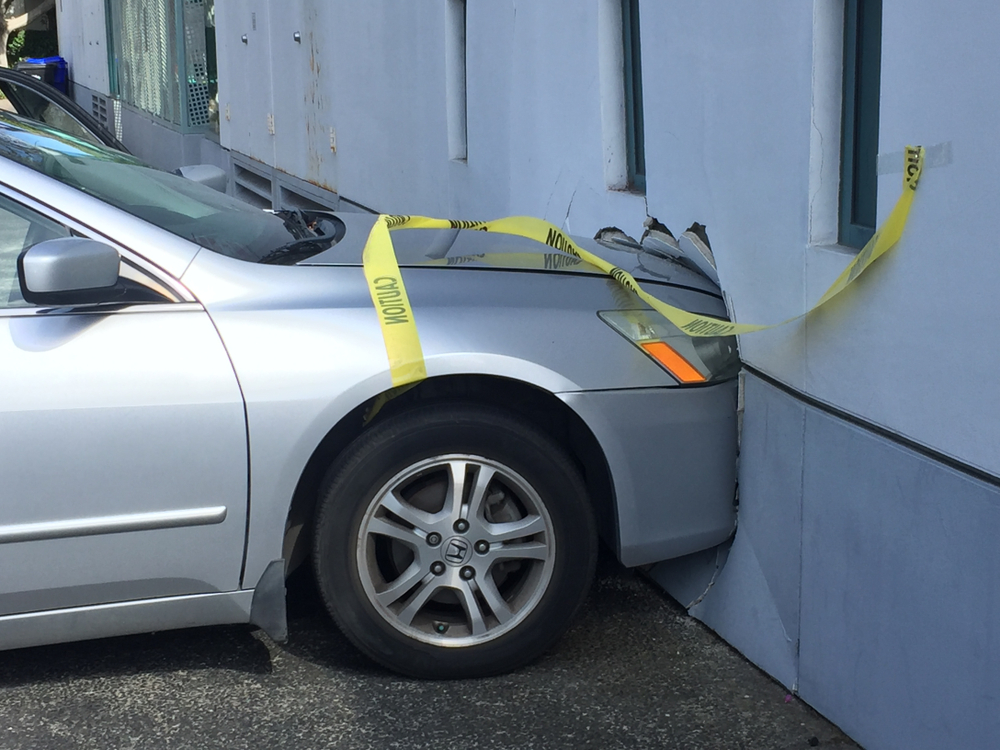
Vehicle-into-building incidents along New Jersey’s commercial corridors require structural engineering documentation before any accurate estimate is possible. And it happens more than you think. We coordinate the engineering assessment and make sure the full structural scope is captured before the insurer has a chance to set a number based on surface observation alone.


Underpaid And Denied Claims

New Jersey policyholders get shortchanged in predictable ways—software that underprices New Jersey labor, aggressive depreciation on older housing stock, damage categories left off because the adjuster moved fast. And when a denial comes, it arrives on official letterhead citing policy language that feels final even when it isn’t. A denial is a position, not a verdict. We review New Jersey claims at no cost. If there’s a case to be made we’ll tell you, and if there isn’t we’ll tell you that too.

Residential And Commercial Properties We Serve In New Jersey

Cape Cods and colonials throughout Monmouth and Ocean counties. Multi-family residential buildings in Newark, Paterson, Jersey City, and Elizabeth. Suburban single-family homes across Bergen, Essex, Morris, and Union counties. Coastal properties from Sandy Hook to Cape May. Historic residential properties in Princeton, Montclair, and the Oranges.

On the commercial side—restaurants, retail, office buildings, warehouses, and mixed-use properties across every commercial corridor in the state. Landlord claims where tenant damage created building owner exposure. Properties where storm damage produced both a property damage and a flood claim under separate policies that both need to be built correctly.

New Jersey property owners who’ve had a covered loss and been shortchanged by the process are exactly who we built this practice to serve. If that’s your situation—we handle it.

How The Claims Process Works With Direct Public Adjusters

We start with a free inspection. No cost, no commitment. If we take the case we build an independent damage assessment entirely separate from whatever the insurer’s adjuster documented, submit the claim, and negotiate directly with the insurance company.

Our fee is a percentage of what we recover above what you’ve already been offered. Nothing upfront. If we don’t get you more, we don’t get paid.

For claim-specific information visit our pages on water damage claims, fire damage claims, storm damage claims, business interruption claims, and underpaid claims.

Frequently Asked Questions: New Jersey Public Adjuster

Does Direct Public Adjusters Handle Claims Across All Of New Jersey Or Just Areas Near New York City?

We handle claims statewide—from Bergen and Hudson counties in the north to Cape May in the south, including the Shore communities, the suburban corridor, the urban centers, and South Jersey. Every region, every property type.

What Makes New Jersey Coastal Storm Claims So Complicated?

Coastal storm claims in New Jersey involve two categories of coverage that often apply to the same loss event—standard homeowner or commercial property coverage for wind damage, and a separate NFIP or private flood policy for water that enters from outside the structure. When a storm produces both, the question of which damage falls under which policy determines what gets paid and by whom. Insurers have a financial incentive to push as much loss as possible into the flood category, especially if the policyholder has lower flood coverage limits or no flood policy at all. Getting the cause of loss documented and allocated correctly before the insurer's adjuster sets the narrative is critical in every coastal New Jersey storm claim.

Can Direct Public Adjusters Reopen A Sandy Claim That Was Settled Years Ago?

For most standard claims the two-year statute of limitations from the date of loss has passed, which closes most legal pathways tied to Sandy directly. However, if a Sandy claim was settled under circumstances that involved bad faith, misrepresentation, or a release that didn't accurately reflect what was being signed away, there may still be avenues depending on the specific situation. It's worth a conversation before assuming nothing can be done.

My New Jersey Claim Was Denied Because The Insurer Called It Gradual Deterioration. Is That The End?

Not necessarily. The gradual deterioration exclusion applies to damage that developed slowly over time through maintenance neglect—not to a sudden failure even on an older system. Insurers apply this exclusion aggressively, especially on older New Jersey housing stock, and they apply it to claims it doesn't legitimately fit. Whether the denial holds up depends on what the physical evidence shows and how the cause of loss is documented. We review these denials regularly and challenge them when the evidence supports a different reading of what happened.

What Types Of Properties Does Direct Public Adjusters Handle Claims For In New Jersey?

Single-family homes, two and three-family residences, multi-family apartment buildings, co-ops, condominiums, and commercial properties including retail, restaurants, offices, and mixed-use buildings. Residential and commercial, owner-occupied and investment properties, anywhere in the state.

How Does Direct Public Adjusters Handle Claims In New Jersey Differently From New York?

The licensing, the process, and the contingency fee structure are the same. What changes is the regional knowledge we bring to the claim—New Jersey's coastal flood dynamics, its specific insurer landscape, its housing stock characteristics by region, and the arguments that adjusters in this market tend to lean on. A claim in Toms River involves different considerations than one in Hoboken, and both look different from a claim in Newark or Princeton. We adjust the approach based on where the property is and what the loss actually involved.

What Does It Cost To Have Direct Public Adjusters Review My New Jersey Claim?

Nothing. We offer a free initial review with no obligation. If we take your case, our fee is a percentage of what we recover above what the insurance company already offered. No upfront cost, no payment unless we get you more.

Have a property damage claim anywhere in New Jersey that wasn't handled fairly? Contact Direct Public Adjusters for a free review—no upfront cost, no obligation, and no fee unless we recover more than what you've already been offered.

Why Direct Public Adjusters

We are licensed public adjusters in New York, New Jersey, Connecticut, and Pennsylvania. New Jersey is a market we’ve worked extensively, and we know how the insurers operating here tend to handle—and mishandle—claims across every region of the state. Contingency fee only. Available 24/7.

We Want to Hear From You

Need a Public Adjuster in New Jersey?
Speak With One Today!

Call Us - +1 (917) 246-2211