Public Adjuster In Connecticut

Public Adjuster In Connecticut

Connecticut is a small state with a concentrated insurance claim landscape that punches above its weight in terms of complexity. The shoreline communities from Greenwich through New Haven to New London face coastal storm and flood exposure that produces some of the most disputed property damage claims in the region. Hartford and the central Connecticut corridor has older urban housing stock with the same aging infrastructure arguments that define claims in Newark and the Bronx. Fairfield County carries some of the highest residential and commercial property values in the country, which means the dollar gap between what an insurer offers and what repairs actually cost is wider here than almost anywhere else in the Northeast. And the quiet residential towns throughout Litchfield County and the state’s rural interior face winter damage scenarios that insurers handle with the same wear-and-tear playbook they use across the region.

Direct Public Adjusters is licensed in Connecticut and handles claims throughout the state. The same documentation-first process, the same independent assessment approach, and the same contingency fee structure we bring to New York and New Jersey applies here. Free inspection, no upfront cost, available 24/7. If your Connecticut property took damage and the settlement figure doesn’t reflect what repairs will actually require, call us before anything gets signed.

Call Us Anytime For A FREE Claim Assessment

Schedule an Appointment

Contact us for a FREE Claim Assessment

Why Connecticut Insurance Claims Require Local Knowledge

Connecticut’s insurance claim landscape is shaped by three things that operate differently here than in neighboring states.

The first is property value. Fairfield County in particular carries residential and commercial real estate values that are among the highest in the country. When an insurer’s pricing software produces an estimate based on national or regional cost averages, the gap between that estimate and what restoration actually costs in Greenwich or Westport is significant. That gap exists on every claim and it compounds on larger losses. Policyholders who don’t know to challenge it leave meaningful money behind.
residential Connecticut neighborhood

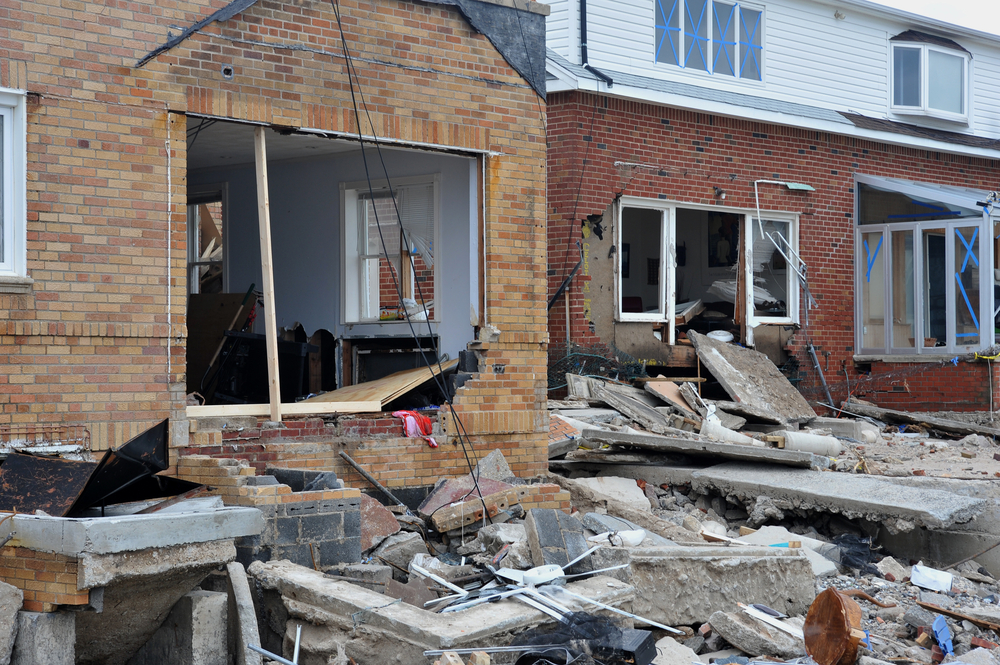
The second is coastal exposure. Connecticut’s shoreline runs from the New York border through Fairfield and New Haven counties before curving around to the southeastern corner of the state. The communities along that shoreline face storm surge risk, nor’easter exposure, and the same flood-versus-wind allocation disputes that define coastal claims in New Jersey and Long Island. When a storm hits the Connecticut coast and produces both wind damage and surge, the insurer’s first move is to push as much loss as possible into the flood category. Documenting what the wind did versus what the water did, and doing that documentation before the insurer’s adjuster sets the narrative, is what determines how much of the loss gets paid.

The third is age. Hartford, Bridgeport, New Haven, and Waterbury all have significant concentrations of older multi-family housing stock where aging plumbing and aging infrastructure are a constant. Insurers operating in these markets apply the pre-existing condition and wear-and-tear arguments aggressively and often on claims that don’t legitimately qualify for those exclusions. A pipe that fails suddenly in a century-old building is still a sudden and accidental loss. The age of the building is not grounds for denial, and adjusters who treat it as one are taking a position that is worth challenging.
Claims We Handle In Connecticut

Water Damage

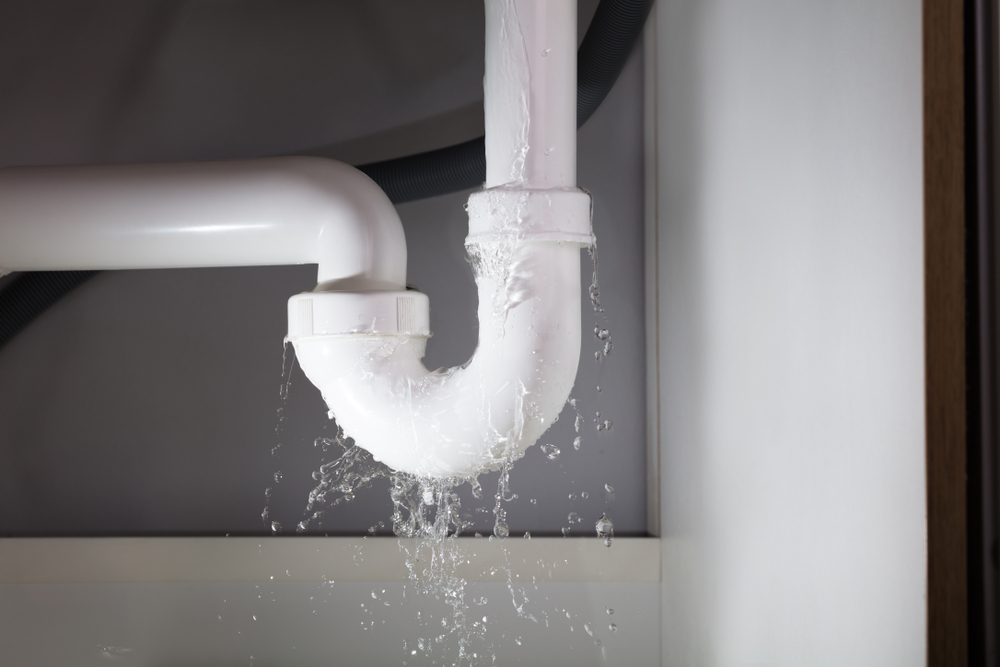
Water damage is the most common claim we handle in Connecticut. Coastal flooding from storm events, burst pipes during Connecticut’s cold winters, roof leaks, appliance failures, and in older multi-family buildings the cascading damage that happens when water moves through shared systems before anyone locates the source. We document the full scope before any cleanup begins, identify what the insurer’s adjuster is likely to miss or minimize, and build the claim around what actually happened.


Burst pipe leaking water under sink representing water damage insurance claim in Connecticut

Fire And Smoke Damage

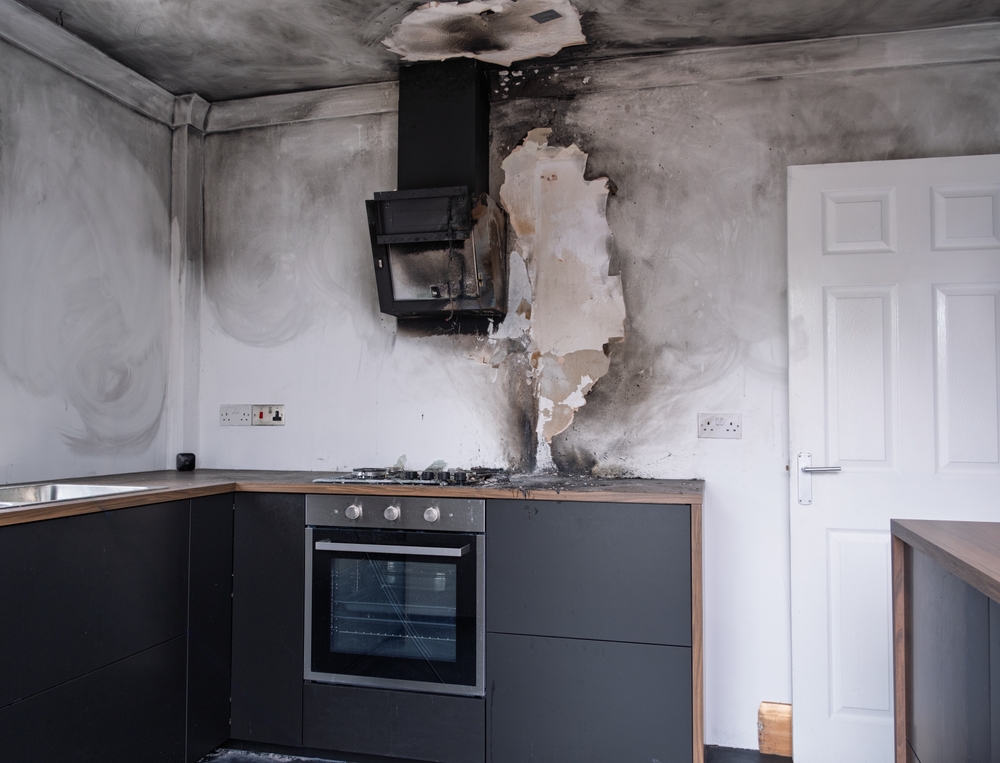
Fire and smoke damage in Connecticut’s older housing stock spreads through shared walls, shared attic spaces, and shared mechanical systems in multi-family and attached residential buildings in ways that a surface walkthrough doesn’t capture. In Fairfield County’s higher-value single-family homes, the cost of restoring custom finishes, specialty materials, and quality construction to pre-loss condition requires documentation and valuation that goes well beyond what standard insurer pricing produces. We document the full scope and make sure the estimate reflects the actual cost of a proper restoration.


Storm And Wind Damage

Storm and wind damage along the Connecticut shoreline involves the same cause-of-loss documentation work that defines coastal claims throughout the region. Inland Connecticut faces a different set of storm claim disputes, primarily around older roofing and siding where insurers reach for the wear-and-tear exclusion as their first response. We counter both with weather verification data and contractor assessments that document what the storm specifically caused.


Closed business sign representing business interruption insurance claim in Connecticut

Business Interruption

Connecticut business owners who take a covered loss need business interruption coverage calculated from their actual financial records. Fairfield County businesses in particular operate at revenue levels that bear no relationship to national industry averages, and a BI calculation built on generic data will consistently undervalue the actual income loss. We build these claims from real numbers.


Accidental Damage

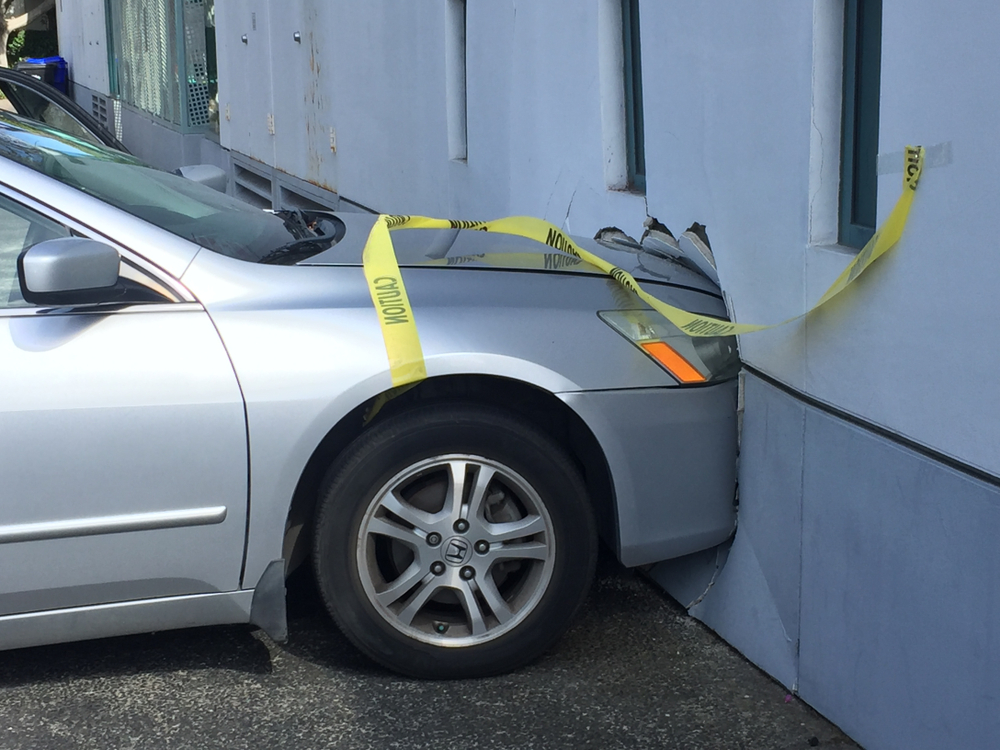
Vehicle-into-building incidents along Connecticut’s commercial corridors require structural engineering documentation before any estimate can be accurate. We coordinate that process from start to finish.

Underpaid And Denied Claims

If your Connecticut claim was denied or settled for less than what your repairs will cost, bring it to us. We review Connecticut claims at no cost and challenge settlements and denials that don’t reflect what the policy actually requires.

Properties We Serve Throughout Connecticut

Shoreline single-family homes and estates throughout Fairfield and New Haven counties. Multi-family residential buildings in Hartford, Bridgeport, New Haven, and Waterbury. Historic residential properties throughout the state’s older suburban towns. Rural single-family homes across Litchfield County and the Connecticut interior.

On the commercial side, restaurants, retail, offices, and mixed-use properties throughout the state. Fairfield County commercial properties where insurer estimates bear no relationship to actual market restoration costs. Landlord claims on multi-unit residential buildings. Properties where a storm or fire event triggered both property damage and business interruption claims that need to be built together.

If you own it, lease it, or manage it anywhere in Connecticut, we handle the claim.

How The Claims Process Works With Direct Public Adjusters

Our team starts with a no-cost inspection. If we take the case, we build our own independent damage assessment entirely separate from whatever the insurer’s adjuster documented. We handle all claim preparation and negotiate directly with the insurance company.

Our fee is a percentage of what we recover above what you’ve already been offered. Nothing upfront. If we don’t get you more, we don’t get paid.

For claim-specific information visit our pages on water damage claims, fire damage claims, storm damage claims, business interruption claims, and underpaid claims.

Frequently Asked Questions: Connecticut Public Adjuster

Does Direct Public Adjusters Handle Claims Across All Of Connecticut Or Just Certain Areas?

We handle claims throughout the entire state including Fairfield County, the Greater Hartford area, New Haven County, the shoreline communities, and the rural interior. Every region, every property type, residential and commercial.

What Makes Fairfield County Insurance Claims Different From The Rest Of Connecticut?

Property values in Fairfield County are among the highest in the Northeast, which means the gap between what insurer pricing software produces and what restoration actually costs is larger here than almost anywhere else in the region. Custom finishes, quality construction, and high-end materials require independent valuation rather than standard line-item pricing, and business interruption claims need to reflect what businesses in this market actually generate rather than national industry averages. Both of these factors consistently produce underpaid claims when insurers are left to calculate the loss without challenge.

Does Standard Homeowner Insurance Cover Storm Surge Damage Along The Connecticut Shoreline?

No. Standard homeowner policies exclude flood damage defined as water entering the property from outside through storm surge, ground water, or surface water accumulation. Separate NFIP or private flood coverage is required for that category of loss. Where it gets complicated is when a storm produces both wind damage and surge simultaneously, which happens regularly along the Connecticut shoreline. The insurer will try to allocate as much loss as possible to the flood category. Getting the cause of loss documented before the insurer's adjuster characterizes it is critical to making sure the wind component gets paid correctly.

My Connecticut Claim Was Denied Based On The Age Of My Property. Is That A Valid Basis For Denial?

Not on its own. The age of a property is not grounds for denying a claim. What matters is whether the damage resulted from a sudden and accidental event or from gradual deterioration. Insurers sometimes conflate these, applying wear-and-tear or gradual deterioration exclusions to losses that don't legitimately qualify for them simply because the property is old. If your claim was denied on these grounds, the denial deserves a close look at the specific policy language and the physical evidence of how the loss actually occurred.

What Does It Cost To Have Direct Public Adjusters Review My Connecticut Claim?

Nothing. We offer a free initial review with no obligation. If we take your case, our fee is a percentage of what we recover above what the insurance company already offered. No upfront cost, no payment unless we get you more.

Does Direct Public Adjusters Handle Commercial Claims In Connecticut?

Yes, including retail, restaurants, offices, and mixed-use properties throughout the state. Commercial claims in Fairfield County in particular involve the same high-value property and business interruption dynamics that make Manhattan commercial claims complex. We build these claims from actual business financials and document physical damage using real market costs rather than national software pricing.

How Long Do I Have To Dispute An Insurance Claim In Connecticut?

Connecticut law generally allows two years from the date of loss to bring legal action against an insurer, though your policy may contain a shorter contractual deadline. The clock runs from the date of the loss, not the date of any settlement or denial, which gives some policyholders more runway than they realize. Waiting significantly reduces your options, so a free review is worth doing sooner rather than later if something about your claim doesn't feel right.

Have a property damage claim anywhere in Connecticut that wasn't handled fairly? Contact Direct Public Adjusters for a free review. No upfront cost, no obligation, and no fee unless we recover more than what you've already been offered.

Why Direct Public Adjusters

We are licensed public adjusters in Connecticut, New York, New Jersey, and Pennsylvania. Connecticut is a market we know well, and we understand how insurers operating here approach claims and where they tend to fall short of what the policy actually requires. Contingency fee only. Available 24/7.

We Want to Hear From You

Need a Public Adjuster in Connecticut?
Speak With One Today!

Call Us - +1 (917) 246-2211