
One of the first questions anyone asks after filing a property damage insurance claim is how long the process is going to take. The honest answer is that it depends on factors that vary significantly from one claim to the next, but there are patterns worth understanding and timelines you have a right to enforce.
New York insurance law sets specific requirements for how quickly insurers must respond at each stage of the claims process. Most policyholders do not know these requirements exist, which means most policyholders do not know when an insurer is operating outside of them.
Within fifteen business days of receiving written notice of a claim, the insurer is required to acknowledge receipt and begin an investigation. Within fifteen business days of receiving a properly executed proof of loss, the insurer must either pay the claim, deny it, or provide written notification that additional time is needed and explain why. If additional time is needed, the insurer must update the policyholder every thirty days on the status of the investigation until a determination is made.
These are not suggestions. They are requirements under New York Insurance Law, and an insurer that consistently fails to meet them is not just slow. It is operating outside the legal framework that governs how claims must be handled in this state.
How Long A Straightforward Claim Takes
In practice, a straightforward residential property damage claim in New York, a burst pipe with contained damage, a clear cause of loss, no coverage dispute, can move through the process in four to six weeks from the date of reporting to a settlement offer. That assumes a responsive insurer, a thorough adjuster inspection, and a policyholder who has their documentation in order. None of those three things are guaranteed.
How Long Complex Claims Take?
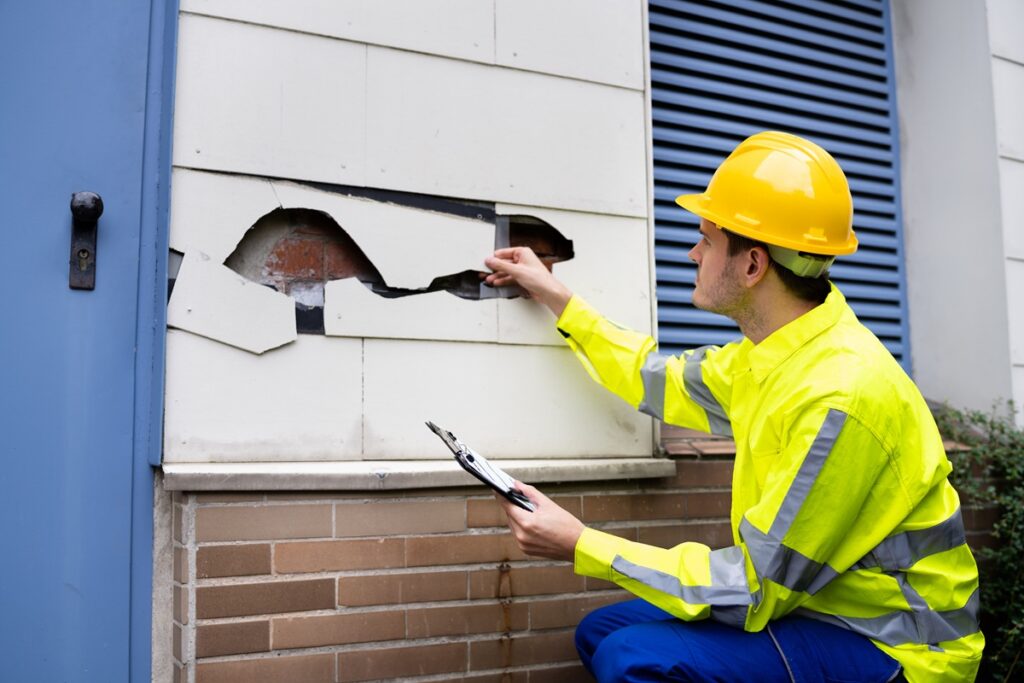
Claims that involve significant hidden damage routinely take longer because the full scope of the loss is not apparent until remediation begins. When a restoration crew opens walls and finds moisture that has been sitting for longer than anyone realized, or when a structural engineer identifies damage that the insurer’s adjuster missed on the initial walkthrough, the claim scope changes and the timeline extends. This is not inherently a problem. A claim that takes longer because the full scope is being properly documented is better than a claim that closes quickly at an inadequate settlement. The problem is when delay serves the insurer’s interest rather than the accuracy of the claim.
Commercial property damage claims almost always take longer than residential ones. Business interruption documentation requires financial records, accountant involvement, and a period of loss calculation that cannot be rushed without getting the number wrong. Multi-policy situations where both a property policy and a flood policy are involved, or where a landlord policy and a tenant policy both have exposure to the same loss, require coordination between multiple carriers that extends the timeline further.
Disputed claims take the longest. When a policyholder pushes back on an initial settlement offer, submits a counter with contractor documentation, requests a re-inspection, or invokes the appraisal clause, each of those steps adds time to the overall process. The appraisal process specifically, from invocation to final award, typically runs sixty to one hundred and twenty days depending on the complexity of the dispute and the availability of the appraisers and umpire involved.
What Consistently Extends Timelines
Late or incomplete documentation is the most common one. A proof of loss that is missing information, a contents inventory that has not been completed, a contractor estimate that has not been submitted — each of these creates a legitimate basis for the insurer to pause the clock on their response obligations. Getting documentation complete and submitted correctly the first time avoids this.
Failure to respond to insurer requests creates similar delays. Insurers are entitled to conduct examinations under oath, request additional documentation, and ask for records that support the claimed losses. A policyholder who does not respond to these requests in a timely way gives the insurer grounds to delay their own response. Staying engaged and responsive throughout the process keeps the clock moving.
Changing the scope of the claim after it has been submitted can reset timelines. When hidden damage surfaces during remediation and needs to be added to the claim, that is a legitimate and often necessary expansion of the scope. But it triggers a new round of inspection and documentation that extends the overall timeline. Having a thorough initial inspection that captures as much of the damage as possible before anything gets submitted reduces how often this happens.
Length And Outcome Are Not The Same Thing
The most important thing to understand about how long a claim takes is that length and outcome are not correlated the way most people assume. A claim that resolves in three weeks at a settlement that does not cover the repairs is worse than a claim that takes four months and produces a settlement that does. The goal is not speed. The goal is an accurate settlement, and the timeline is the byproduct of getting there.
If your New York property damage claim has been open for months with no movement, if the insurer has missed the response deadlines the law requires, or if you accepted a fast settlement that did not cover what your repairs actually cost, the situation is worth reviewing. Find out what your options are by visiting our underpaid and denied claims page. We handle claims across all five NYC boroughs and throughout New York, New Jersey, Connecticut, and Pennsylvania. Free consultation, no fee unless we recover more.